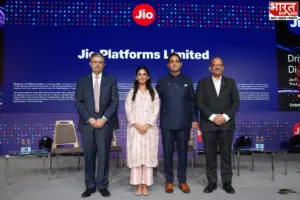


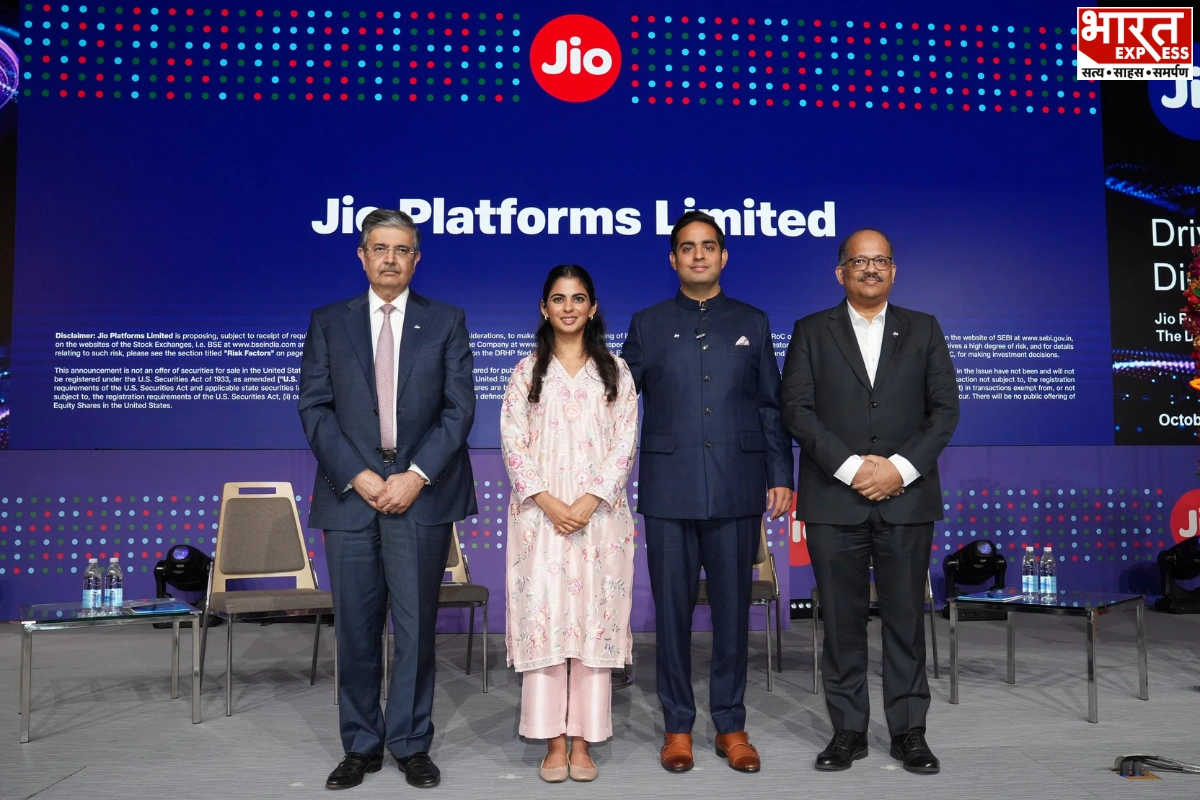
Jio Platforms’ initial public offering has received encouraging assessments from several market analysts following the announcement of its price band.
Experts estimate that the shares could list at a premium of 15–20%, although the eventual outcome will depend on market conditions and investor demand.
Emkay Research assigned the issue a ‘Subscribe’ rating in its October 16 report, describing the valuation as reasonable relative to Jio’s market leadership, pricing power, execution capabilities and expansion opportunities.
Swastika Investmart has also recommended subscribing to the IPO. Its analysis places Jio’s price-to-earnings ratio at approximately 33.3 times FY26 earnings at the upper price band, against 40.7 times for Bharti Airtel, suggesting an 18% valuation discount.
Other estimates put Jio at around 33.5 times earnings and Airtel at 38.9 times, making Jio approximately 14% cheaper. Analysts, however, caution that some expected growth may already be reflected in the valuation.
Analysts see the completion of much of Jio’s heavy 5G investment cycle as a significant advantage. Emkay Research said capital expenditure fell from 48.8% of revenue in FY24 to 23.3% in FY26.
Jio generated approximately ₹32,500 crore in free cash flow during FY26. Lower requirements for large-scale investment could allow the company to strengthen its cash position further.
Beyond mobile services, analysts identify home broadband, enterprise solutions, cloud computing, artificial intelligence and international technology expansion as potential growth drivers.
Emkay highlighted home broadband and Jio’s in-house technology platform as important opportunities.
Reliance Industries Limited shares rose around 3.4% after Jio announced its price band on October 15. Investors are now assessing whether Jio’s separate listing could unlock additional value for RIL shareholders.
To read more such news, download Bharat Express news apps