

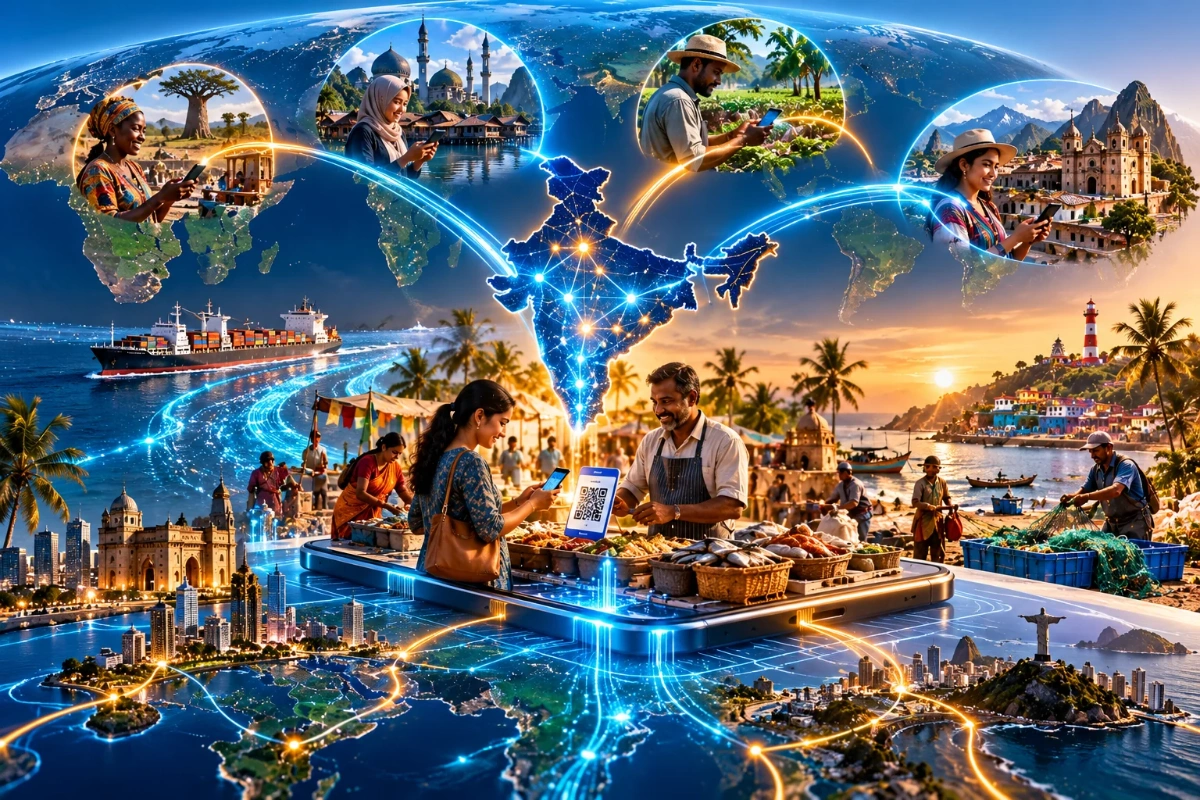
AI Generated Image
The Unified Payment Revolution: How India’s Digital Pipeline Inspired the Global South
Digital payments are no longer just a banking convenience; they are becoming public infrastructure. India’s UPI-led model shows how identity, real-time payments, data exchange, open APIs and mobile access can work together as a digital pipeline that moves money, builds trust and connects services across an economy. For the Global South, the lesson is not to copy one country’s system exactly, but to build interoperable, inclusive and locally governed digital payment systems that allow banks, fintechs, governments, merchants and citizens to participate on common rails.
What Is the Unified Payment Revolution?
The unified payment revolution is the shift from fragmented, closed payment channels to interoperable real-time payment networks that connect multiple institutions, apps, merchants and users through shared rules. In practical terms, it means a person can pay from one bank account to another, settle a merchant bill, receive a government benefit or complete an online purchase through a familiar digital interface without requiring each provider to establish a separate payment relationship.
India’s Unified Payments Interface, widely known as UPI, became the clearest example of this shift because it turned instant bank-to-bank payments into a mass-market behaviour. UPI was launched in 2016 by the National Payments Corporation of India (NPCI). Official government material describes it as a real-time payment system that brings multiple bank accounts, fund transfers and merchant payments onto one platform, with round-the-clock availability and security features such as two-factor authentication and encryption.
The phrase matters because it describes more than faster transactions. A unified payment model changes who can participate. Instead of requiring every consumer to use a single wallet, card network, banking app or cash counter, it allows multiple payment solution providers to innovate on a common backbone. Banks retain a trusted role, fintech apps compete on user experience, merchants gain broader acceptance, and users have a simpler way to move money.
This is why the model has attracted attention across the Global South. Many developing economies face similar constraints: high dependence on cash, uneven access to banking, costly merchant acceptance, fragmented government service delivery and limited trust in digital channels. A unified architecture offers a way to improve digital payment systems without waiting for every institution to modernise at the same pace.
India’s Digital Pipeline Is Bigger Than One Payment App
UPI is often discussed as though it were only a payment interface, but its wider significance comes from the infrastructure surrounding it. India’s digital public infrastructure (DPI) combines several layers: identity, payments, data exchange, service delivery and assisted access. Government sources describe the country’s DPI approach as open, interoperable and scalable, with Aadhaar for identity, UPI for payments, and DigiLocker and API Setu for data exchange and service integration.
That combination matters because a payment is rarely just a payment. A customer may need identity verification before opening an account. A merchant may need a low-cost acceptance method before switching from cash. A government may need beneficiary authentication before transferring a subsidy. A lender may need permissioned data to evaluate a small business. The easier it becomes to connect these steps through standardised infrastructure, the simpler it is to build integrated payment services for end users.
Identity Creates the Trust Layer
Digital identity gives people a way to prove who they are through online and assisted channels. In India, Aadhaar has become one of the foundational layers used across services, and a 2026 government release reported that more than 144 crore Aadhaar IDs had been generated. The same release described India’s DPI as supporting financial inclusion, digital inclusion, governance and service delivery.
For countries studying the model, the important point is not that every nation needs the same biometric or institutional design. Reliable, lawful and accessible identity tools can make payment processing solutions easier to use by supporting the onboarding of individuals and businesses. Without that trust layer, digital financial services can become slow, expensive or exclusionary.
Payments Create the Transaction Layer
UPI created a shared layer for instant interbank transfers and merchant payments. By July 2026, official figures reported 741 live banks on the UPI ecosystem, 2,365.8 crore transactions during the month and a transaction value of ₹29.87 lakh crore. NPCI’s monthly statistics also showed continued growth in September 2026, with 756 banks live on UPI, 24,068.38 million transactions and a transaction value of ₹29,37,396.67 crore.
Scale alone does not tell the full story. The more important design feature is interoperability: users can transact across banks and apps because the network follows common rules and routing mechanisms. This creates a market in which payment solution providers compete on user experience, reliability, customer support, rewards, fraud controls, merchant tools and payment integration rather than exclusive access to the payment rail.
Data Exchange Creates the Service Layer
The data layer helps payments become part of larger service journeys. API Setu, for example, is described by the Government of India as a platform that supports open APIs and seamless integration of government services, with thousands of APIs published by central and state departments.
For citizens, this can mean less paperwork. For businesses, it can mean faster verification or simpler compliance processes. For payment providers, it means digital payment systems can be embedded into tax, welfare, licensing, billing, insurance, credit, education and healthcare interactions. The result is not merely cashless payment; it is the ability to connect payment events with legitimate service transactions.
Access Channels Keep the System Inclusive
A unified payment revolution will fail if it serves only urban smartphone users. India’s model has expanded through mobile apps, QR codes, feature-phone options, assisted service centres and government platforms. Official materials list UPI 123PAY for feature-phone users, UPI Lite for low-value transactions, UPI AutoPay for recurring mandates, and credit-line or credit-card-linked use cases as later innovations in the ecosystem.
This principle is central to the Global South. Multi-channel payments are not an optional extra; they are a requirement for inclusion. A farmer, domestic worker, street vendor, migrant worker, small shop or online seller may need a different interface, but the underlying payment should still travel across the same trusted rails.
Why Did UPI Change Payment Processing Solutions?
UPI changed payment processing by separating the payment rail from the customer interface. Banks, fintech apps and other participants could connect to a shared system, while users could choose the app or channel that worked best for them. This design encouraged competition at the edge and standardisation at the core, striking a balance that many emerging markets need.
Traditional payment systems often develop in silos. Card networks have their own rules and hardware requirements. Wallets may work only within one provider’s ecosystem. Bank transfers may be reliable but inconvenient for everyday retail use. Cash is widely accepted but difficult to trace, secure, automate or use remotely. UPI showed that instant account-to-account payments could become simple enough for everyday use while still operating through regulated financial institutions.
The World Bank has described India’s contribution as reframing instant payments as open and interoperable infrastructure. It noted that UPI embedded fast payments into a wide range of retail transactions, from street vendors to online purchases, combining bank infrastructure with fintech innovation.
The Old Model and the Unified Model
| Payment Challenge | Fragmented Model | Unified Payment Model |
|---|---|---|
| Customer access | Users often need the right bank, wallet, card or cash option | Users transact through participating apps and accounts on shared rails |
| Merchant acceptance | Merchants may need multiple devices, contracts or settlement arrangements | QR-based and app-based acceptance can reduce onboarding friction |
| Innovation | Each provider builds separate, closed-loop experiences | Providers innovate using common standards and APIs |
| Government transfers | Delivery may depend on separate databases and manual processes | Identity, account and payment layers can be linked more efficiently |
| Payment integration | Businesses integrate channels individually | Platforms can support multi-channel payments through standardised processes |
| Inclusion | Rural users, low-income groups and small merchants can be left behind | Design can accommodate feature phones, assisted channels and low-value payments |
This shift also changes how businesses approach payment integration. A retailer no longer has to treat digital payments as a separate counter experience. A biller can trigger a payment request. A subscription business can use mandates. A marketplace can embed checkout. A government department can incorporate payment confirmation into a citizen-service workflow. Payment becomes a programmable part of business operations.
Interoperability Reduces Network Lock-In
Interoperability is the driving force behind the unified payment revolution. In an interoperable system, the value of joining does not depend on persuading every friend, customer, supplier or merchant to use the same private app. The network itself carries transactions across participating institutions.
This is especially powerful in emerging economies because it avoids duplicating infrastructure. Instead of every provider building a separate merchant base and user base, providers can connect to shared rails and differentiate themselves through service quality. This can make digital payment systems more competitive and resilient, provided governance keeps access fair and security robust.
Open Participation Speeds Adoption
UPI’s rise was driven not only by regulation and technology, but also by the user experience. Simple payment identifiers, QR codes, bank-linked accounts, mobile-first design and competition between apps made digital payments feel familiar. The World Bank noted that user experience, open participation and merchant acceptance helped turn digital payments from a technical option into a cultural norm.
For businesses, this is a key lesson. Payment processing solutions succeed when they become almost invisible within the customer journey. The fewer steps users need to understand, the more likely they are to adopt the service. Similarly, the lower the cost and complexity of acceptance for merchants, the faster the ecosystem can grow.
The Global South Sees a Practical Development Blueprint
The Global South is not a single market. Its countries have different regulatory systems, banking structures, languages, income levels, mobile penetration rates, political institutions and consumer habits. Nevertheless, many share a common need: digital infrastructure that can reach people and small businesses at scale without depending entirely on proprietary systems.
The World Bank’s Global Digital Public Infrastructure Program frames DPI around digital identity, payments and secure data sharing. It states that the programme supports more than 80 countries in improving access to services and opportunities. It also notes that major gaps remain, including billions of people lacking digital IDs for online transactions and the limited availability of fast, inclusive payment systems in lower-middle-income and upper-middle-income countries.
India’s experience has therefore become influential because it suggests a third path between entirely state-run service portals and purely private financial platforms. Shared infrastructure can be guided by public-interest objectives, support private innovation and be reused widely. This is why policymakers increasingly discuss digital public infrastructure not simply as a software product, but as a model for governance and architecture.
India’s Model Travels as Principles, Not a Clone
A country should not simply import UPI, Aadhaar or another system without adapting it to local laws, institutions and social conditions. Payment habits, privacy expectations, banking readiness, telecommunications access, cybersecurity capacity and public trust vary widely. The stronger lesson is architectural: build rails that are open enough to encourage innovation, regulated enough to protect users and modular enough to evolve.
Government sources state that India has signed memoranda of understanding and agreements with 24 countries to cooperate on India Stack and digital public infrastructure. These agreements cover areas such as digital identity, digital payments, data exchange frameworks and service delivery systems. The same source emphasises that the objective is collaboration on architecture and design principles, rather than simply exporting a fixed product.
Cross-Border Payment Possibilities Are Expanding
UPI’s international footprint has also grown. A 2026 government backgrounder reported that UPI was accepted in 11 countries, with Greece and the Maldives among the latest additions. It described deployments or linkages involving Bhutan, Nepal, Singapore, the UAE, France, Sri Lanka, Mauritius, Qatar, Cambodia, Greece and the Maldives.
For economies with large migrant populations, cross-border use cases matter. Remittances, tourism, student payments, small-scale trade and diaspora commerce can all benefit from faster, more transparent payment rails. However, cross-border payment integration is more complex than domestic interoperability because it involves currency conversion, anti-money laundering rules, settlement arrangements, sanctions screening, consumer protection and bilateral or multilateral governance.
Design Principles Behind a Scalable Payment Pipeline
A unified payment revolution depends on design choices that may appear technical but have significant economic and social implications. The following principles explain why India’s model has become influential and what other countries can adapt.
1. Build Public Rails, Not a Public Monopoly
The core rail should be trusted, standardised and governed in the public interest. That does not mean the government must build every app or own every customer relationship. In a healthy ecosystem, public or regulated infrastructure defines the basic rules, while banks, fintechs, merchants and service providers create competing experiences on top.
This structure can support innovation without forcing every participant to recreate the foundations. It can also prevent a single private network from becoming the gatekeeper for essential payments. The challenge is to keep access open while enforcing strong risk controls.
2. Make Interoperability Non-Negotiable
Interoperability should be built into the system from the beginning. Users should not need to know whether the payer and payee use the same app, bank or device. Merchants should not need a separate acceptance method for every major provider.
This is where common APIs, standardised identifiers, shared dispute rules and reliable switching infrastructure become critical. They reduce complexity for payment solution providers and make payment integration easier for businesses. They also create a fairer environment for smaller banks and fintechs that cannot build closed networks at national scale.
3. Support Multi-Channel Payments from Day One
A country with uneven internet access, device ownership, literacy levels and banking penetration cannot rely on a single smartphone app. Multi-channel payments can include smartphone apps, QR codes, USSD or feature-phone flows, assisted agent networks, bank branches, merchant devices and web checkout. The goal is not to make every channel identical, but to ensure that each connects to the same trusted payment layer.
This approach supports inclusion and resilience. If one channel experiences an outage, customers may still have another way to pay or receive funds. For businesses, multi-channel design allows customers to move between online and offline journeys without disrupting the payment experience.
4. Keep the User Experience Simple
Infrastructure succeeds only when people use it. UPI’s popularity grew because the payment experience became quick, familiar and adaptable to everyday behaviour. QR scanning, mobile numbers, payment identifiers, bank-linked apps and instant confirmation made the system understandable, even though the underlying architecture was complex.
Good design reduces cognitive load. A small merchant should not need to understand settlement architecture to accept a payment. A customer should not need to memorise bank details to send money. A government beneficiary should not have to navigate multiple portals to receive support.
5. Treat Security and Trust as Product Features
Trust is not just a back-end control; it is part of the user experience. People need to know when a payment is authorised, when it is complete and how to raise a complaint. Merchants need predictable settlement and effective fraud controls. Regulators need visibility into systemic risk.
Security must include authentication, encryption, monitoring, user education, liability rules, dispute handling and cyber resilience. If users feel unsafe, adoption slows. If providers face unclear rules, innovation slows. Strong governance is therefore a growth strategy, not an afterthought.
6. Design for Small-Value, High-Frequency Transactions
Many payment systems are designed around large, formal transactions. Inclusive digital payment systems must also work for a cup of tea, a bus ride, a market purchase, a school fee or a neighbourhood service. Low-value payments are where digital behaviour becomes habitual.
This has implications for costs, uptime, latency and merchant onboarding. If fees are too high, small merchants may resist adoption. If authentication is too burdensome, users may return to cash. If settlement is unpredictable, trust declines. A unified payment rail must make everyday payments economically viable.
Checklist for Countries Building Unified Digital Payment Systems
A national payment transformation needs more than a technical launch. It requires careful sequencing, effective governance, appropriate incentives and continuous refinement.
- Map Payment Pain Points First: Identify where cash dominates, transfers are slow, merchants resist digital acceptance and government payments lose efficiency.
- Define the Public-Interest Mandate: Clarify whether the goals are inclusion, competition, lower costs, better government service delivery, formalisation, innovation or a combination of these.
- Create Interoperable Standards: Establish common APIs, identifiers, messaging formats, settlement rules, dispute processes and certification requirements.
- Bring Banks and Non-Banks into the Architecture: Banks provide regulated accounts and trust, while fintechs and payment solution providers often contribute speed, design, distribution and customer engagement.
- Plan for Multi-Channel Payments: Include smartphones, QR codes, web platforms, feature phones, assisted channels and merchant tools so the system does not exclude users.
- Build Privacy and Data Protection In Early: Payment data is sensitive. Consent, purpose limitation, cybersecurity, retention rules and grievance redress should be designed before the system reaches scale.
- Align Incentives for Merchants: Digital acceptance must be affordable, easy to reconcile and useful for business operations such as inventory management, credit, invoicing and tax compliance.
- Invest in Trust and Literacy: Users need clear guidance, fraud warnings, complaint channels and confidence that failed transactions will be handled fairly.
- Measure Adoption Beyond Headline Volumes: Track rural use, gender gaps, small-merchant acceptance, failed transactions, fraud rates, dispute resolution and accessibility.
- Keep the Architecture Modular: New use cases will emerge, including recurring payments, offline payments, credit-linked payments, cross-border remittances and government-to-person transfers.
Business Impact: From Checkout Tool to Growth Infrastructure
For businesses, the unified payment revolution turns payments from a back-office function into a growth platform. When payment integration is clean and reliable, a company can sell across channels, reduce cash handling, reconcile transactions faster and improve customer journeys. This applies to marketplaces, utilities, education providers, healthcare networks, transport systems, insurers, lenders, subscription companies and neighbourhood retailers.
Integrated payment services are particularly valuable when a business needs to combine several actions: identify a customer, issue a bill, collect a payment, confirm settlement, update records, send a receipt and handle refunds or disputes. In a fragmented system, each step may require separate vendors and manual reconciliation. In a unified system, a payment event can trigger a more automated service workflow.
Where Businesses Feel the Difference
- Online Checkout: Customers can pay through familiar bank-linked apps or payment identifiers instead of entering lengthy account details.
- Offline Retail: QR acceptance can reduce dependence on card terminals and cash change, particularly for small merchants.
- Recurring Billing: Mandates and autopay flows can support subscriptions, utilities, insurance premiums, school fees, loan repayments and membership renewals.
- Collections: Businesses can send payment requests, reconcile incoming funds and reduce follow-up work.
- Disbursements: Employers, platforms, governments and institutions can transfer funds more efficiently to verified accounts.
- Embedded Finance: Lenders and platforms can connect payment histories, consented data and service workflows to develop more relevant financial products.
The strategic question is no longer, ‘Which payment method should we add?’ It is, ‘How do we design payment integration so that money movement supports the entire customer experience?’ That is why modern payment processing solutions must support APIs, dashboards, reconciliation, fraud controls, refunds, dispute handling, settlement reporting and multi-channel payments.
How Should Payment Solution Providers Adapt?
Payment solution providers should move from channel-by-channel processing towards orchestration across payment rails, apps, banks and customer touchpoints. A provider that offers only a payment button may be useful, but one that helps businesses manage identity, authorisation, routing, reconciliation, risk, reporting and customer communication offers substantially greater value.
The India-inspired model rewards providers that understand both infrastructure and user experience. Although the payment rail may be standardised, merchants still need onboarding, integration support, analytics, settlement clarity, dispute workflows, fraud monitoring and customer support. Governments and large enterprises also need scalability, reliable uptime, auditability and regulatory compliance.
Capabilities That Matter Most
- API-First Integration: Developers should be able to embed payments into websites, apps, invoices, point-of-sale systems and service platforms.
- Payment Orchestration: Businesses may need to route transactions across UPI-style rails, cards, wallets, bank transfers and cross-border methods.
- Multi-Channel Support: Providers should support online, offline, mobile, QR-based, recurring, assisted and bulk payment use cases.
- Real-Time Status Visibility: Users and merchants need clear confirmation, failure reasons, refund status and settlement timelines.
- Reconciliation Tools: Automated reports reduce manual work and help finance teams match orders, invoices and bank entries.
- Fraud and Risk Controls: Real-time monitoring, transaction velocity checks, authentication flows and alerts help protect users and merchants.
- Compliance Readiness: Providers must adapt to local KYC, anti-money laundering, data protection, consumer protection, tax and payment-system rules.
- Scalable Support: As digital payment systems grow, complaint handling and operational resilience become central to trust.
A provider’s competitive advantage will increasingly come from making complexity manageable. Businesses do not want to become payment infrastructure experts. They want reliable, integrated payment services that work across customer segments, regions and channels.
The Inclusion Promise and Its Limits
The strongest argument for unified payments is inclusion. When digital payments are instant, accessible and widely accepted, people outside traditional financial centres can participate more fully in economic life. Small merchants can accept digital payments. Households can receive transfers. Workers can be paid faster. Governments can deliver benefits with greater traceability. Platforms can serve users who previously relied on cash.
The World Bank’s discussion of India’s fast-payment experience highlights UPI’s role in making real-time payments usable across everyday transactions. It also notes that person-to-merchant transactions have become a major driver of recent growth.
However, inclusion is not automatic. A digital payment rail can reproduce exclusion if users lack phones, connectivity, documentation, digital literacy, language access or trust. It can also create new risks, including scams, mistaken transfers, surveillance concerns, data misuse, account takeovers and overdependence on a few dominant apps. The unified payment revolution must therefore be judged not only by transaction volumes, but also by who benefits and who remains excluded.
Inclusion Requires Deliberate Safeguards
A well-designed payment ecosystem should provide:
- Accessible onboarding for users without advanced smartphones, formal employment or high levels of literacy.
- Clear consent and privacy protections to prevent payment data from being exploited beyond legitimate purposes.
- Low-cost merchant acceptance that works for microbusinesses as well as large retailers.
- Strong dispute resolution for failed, mistaken or fraudulent transactions.
- Language and disability access across apps, assisted channels and customer support.
- Competition safeguards to prevent a few dominant apps from controlling the user experience or merchant terms.
- Offline or low-connectivity options where network access is unreliable.
- User education covering fraud risks, PIN safety, payment confirmation and complaint procedures.
These safeguards may appear operational, but they are central to adoption. People trust systems that protect them when something goes wrong.
Governance Is the Real Infrastructure
Technology attracts most of the attention, but governance determines whether a unified payment system remains trustworthy. Governance defines who can participate, how fees work, how data is protected, how disputes are resolved, how outages are handled, how fraud is monitored and how innovation is approved.
A payment rail becomes systemically important when it reaches national scale. Outages can affect daily commerce. Fraud waves can damage trust. Poorly designed incentives can discourage banks or merchants. Weak privacy rules can trigger public backlash. Concentrated app markets can reduce competition, even when the underlying rail remains open.
Core Governance Questions
- Who owns and operates the switching infrastructure?
- Which regulator supervises the payment system, banks, fintechs and data flows?
- What are the rules for non-bank participation?
- How are fees set, reviewed and distributed among participants?
- What uptime and security standards apply to banks, apps and processors?
- How are failed transactions reversed or investigated?
- What liability applies when fraud occurs?
- How is payment data stored, shared, anonymised or deleted?
- How are new features tested before mass rollout?
- How does the system prevent exclusion, market concentration or political misuse?
Countries inspired by India’s digital pipeline should devote as much attention to these questions as they do to software design. Payment infrastructure is not neutral once it becomes part of everyday life. It shapes competition, privacy, public service delivery and economic participation.
The Next Phase: Domestic Rails Meet Global Networks
The next stage of the unified payment revolution will likely focus on connections between domestic systems. Many countries are building or upgrading instant payment rails, and the long-term opportunity lies in linking them for remittances, tourism, small-business trade and regional commerce. India’s expanding UPI footprint shows the direction of travel, but it also highlights the complexity of cross-border deployment.
Domestic real-time payments are challenging enough. Cross-border systems must coordinate exchange rates, settlement currencies, compliance screening, consumer protection, operating hours, dispute rules and data localisation requirements. For the Global South, regional collaboration may prove as important as national infrastructure.
This is where the India-inspired approach can influence global standards. If countries build interoperable, API-enabled, regulated and inclusive systems at home, they will be better positioned to connect internationally. A payment rail designed solely for a closed domestic app will struggle to become part of a larger network. A rail designed around common standards can reach further.
What the Global South Can Take from India’s Experience
India’s payment story is powerful because it combines scale with adaptability. UPI did not replace every payment method, nor did it solve every financial inclusion challenge. However, it demonstrated that a public-interest payment rail can become a platform for mass adoption when banks, fintechs, merchants, government services and users all have reasons to participate.
For the Global South, the most useful lessons are practical:
- Build digital public infrastructure as a set of reusable layers, not isolated apps.
- Treat payments, identity and data exchange as connected foundations.
- Make interoperability a policy choice, not an optional feature.
- Allow payment solution providers to compete on user experience while following common standards.
- Support multi-channel payments so rural, low-income, feature-phone and assisted users are not excluded.
- Design payment integration for businesses, governments and platforms, not just consumers.
- Measure success through trust, inclusion, resilience and competition, as well as transaction volumes.
- Adapt the model to local institutions rather than importing it unchanged.
The unified payment revolution is ultimately a revolution in governance and design. It asks countries to treat payments as infrastructure for opportunity: open enough to encourage innovation, safe enough to sustain trust and inclusive enough to reach people who were previously considered too costly to serve. India’s digital pipeline has offered a visible proof point. The next chapter belongs to the countries and providers that translate these principles into systems suited to their own economies.
Also Read: Youth Driving Circular Economy In India’s Coasts
To read more such news, download Bharat Express news apps