

AI Generated Image
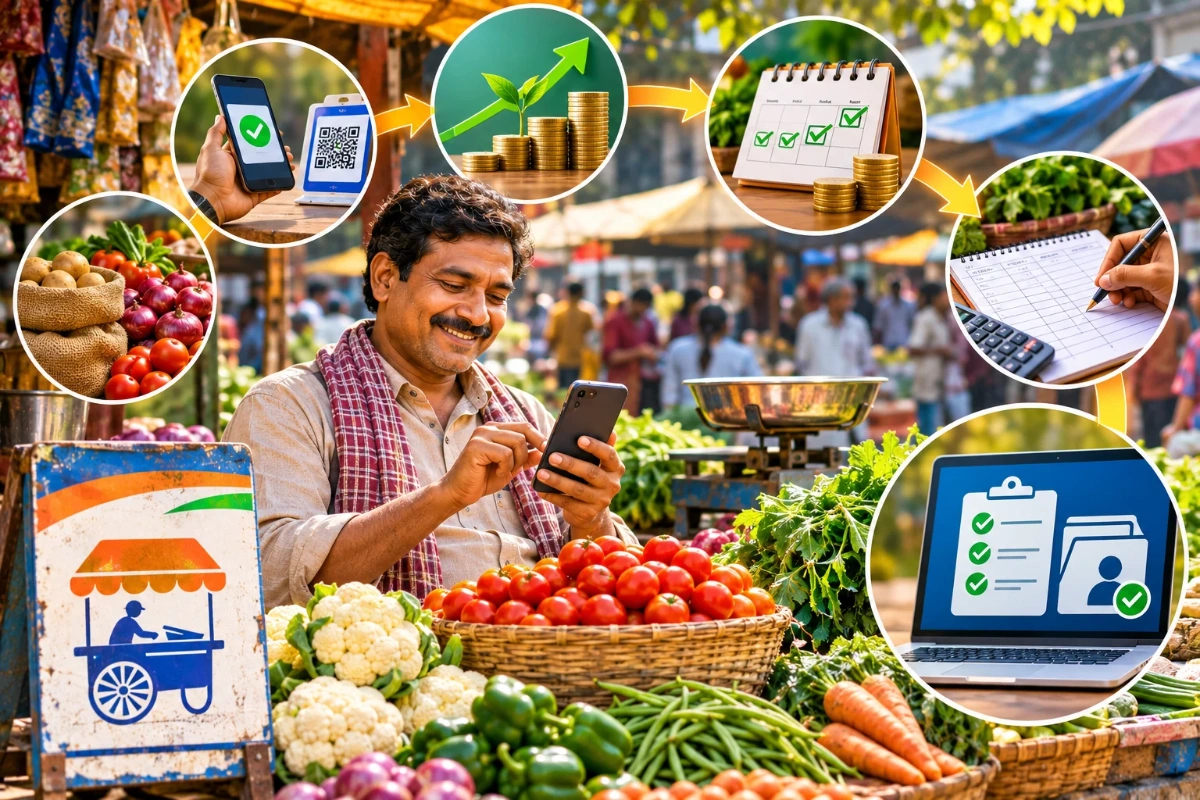
One Market Day With a Street Vendor Who Took a PM SVANidhi Loan
PM SVANidhi provides eligible street vendors with collateral-free working capital loans to help them restart, sustain or grow their businesses. This article follows an illustrative vegetable seller through a market day, showing how stock purchases, sales, expenses and repayments fit together before explaining the application process. The scheme offers progressive loans of up to Rs 15,000, Rs 25,000 and Rs 50,000, subject to eligibility and repayment requirements.
What Does a PM SVANidhi Loan Offer a Street Vendor?
A PM SVANidhi loan is a working capital term loan for eligible street vendors, provided by participating lenders without collateral. The borrowing sequence starts with a smaller loan and allows access to higher tranches after full repayment of the preceding loan. It is repayable credit, not a grant or an automatic entitlement to Rs 50,000.
| Loan Stage | Maximum Loan Amount | Repayment Tenure |
|---|---|---|
| First tranche | Rs 15,000 | 12 months |
| Second tranche | Rs 25,000 | 18 months |
| Third tranche | Rs 50,000 | 36 months |
Repayment is made through monthly instalments. These are the revised limits: the Cabinet’s August 27, 2025 decision increased the first and second tranches from Rs 10,000 and Rs 20,000, respectively, while retaining the third-tranche ceiling of Rs 50,000. Older material showing the previous limits should not be treated as the current offer.
For the seller in this illustration, the purpose is straightforward: finance stock before customers arrive, then manage the proceeds without confusing turnover with the money available to spend.
Before Opening: Match the Stock Purchase to the Payment
The illustrative seller begins with a purchase list rather than a sales target. Tomatoes, potatoes, onions and leafy vegetables each receive a separate ledger entry. The record includes the quantity, purchase price, supplier, payment method and whether any amount remains payable.
This is where the working capital loan becomes visible in the accounts. A loan disbursement belongs in the borrowing record, not in sales. A payment to the wholesaler is recorded against the stock purchased, whether the money leaves the bank account digitally or comes from cash already withdrawn.
The seller’s illustrative ledger uses these fields:
- Stock received: Item, quantity, unit cost and total purchase cost.
- Supplier payment: Cash or digital payment, date and transaction reference, where available.
- Unpaid purchases: Any outstanding supplier balance, recorded separately from paid stock.
- Transport and handling: Costs of bringing the goods to the selling point.
- Available funds: Cash and bank balances remaining after the morning transactions.
Suppose the seller withdraws cash and then pays the supplier. The withdrawal is a transfer between the seller’s own bank and cash balances, not an additional business expense. The supplier payment is recorded once, preventing the same purchase from being counted twice.
The practical benefit is visibility. Before trading starts, the seller can see how much money has been converted into stock, how much remains available and which obligations still need to be paid. This illustration does not assume that every purchase will sell or that borrowing guarantees a better profit margin.
During Trading: Separate Sales From Money Movements
At the stall, the illustrative seller accepts cash and digital payments. Each completed sale increases the sales total, but the corresponding money appears in different places. Cash goes into the cash balance, while a confirmed digital receipt is included in the bank-side reconciliation.
For this walkthrough, the seller maintains a sales tally alongside payment records. This makes it possible to track the day’s transactions without publishing customer names, phone numbers or account identifiers. No actual customer transactions are, however, represented here.
A useful reconciliation follows this sequence:
- Add recorded cash sales to the opening cash balance.
- Deduct cash purchases, operating payments, deposits and household withdrawals under their correct categories.
- Match digital sales to confirmed receipts, checking unresolved or reversed transactions separately.
- Keep transfers between the seller’s own accounts out of the sales total.
- Investigate any difference rather than adding an unexplained balancing entry.
In the illustration, a customer payment and a transfer from the seller’s other account could both appear as incoming bank entries. Only the customer payment is sales income. Treating every credit as turnover would overstate the business’s performance.
This distinction matters when assessing whether another borrowing cycle is manageable. A busy payment history is not, by itself, evidence of surplus cash. The closing ledger needs to show what remains after stock purchases, expenses, household withdrawals and repayment commitments.
At Closing: Account for Expenses, Stock and Repayment
The seller now brings the records together. Transport, packaging and other operating payments are entered separately from merchandise purchases. Any household withdrawal is marked as a drawing rather than disguised as a stall expense.
Unsold vegetables remain part of the stock reconciliation. The illustrative ledger distinguishes goods carried forward from those spoiled or discarded, so missing stock does not silently become an assumed sale. A physical count gives the seller something concrete to compare with the purchase and sales records.
| Illustrative Ledger Entry | Supporting Record | Treatment in This Walkthrough |
|---|---|---|
| Morning stock purchase | Supplier bill or purchase note | Stock received and supplier payment recorded separately |
| Cash sales | Sales tally and cash count | Sales reconciled with cash movements |
| Digital sales | Confirmed transaction history | Sales matched to corresponding receipts |
| Operating expenses | Receipts or dated expense notes | Business costs separated from stock and drawings |
| Loan instalment | Bank debit and loan statement | Payment checked against the lender’s loan account |
| Remaining or spoiled stock | Closing stock count | Carry-forward stock separated from losses |
For repayment, the illustration assumes an instalment falls due on this market day. It does not suggest that PM SVANidhi requires daily instalments. The seller checks the bank debit against the loan statement rather than assuming that a payment instruction succeeded. Actual principal, interest, outstanding balance and due dates must be confirmed through the lender’s records. Scheme loans are repayable through monthly instalments.
The seller’s closing review uses a simple cash bridge: opening funds, plus receipts, minus payments, equal closing funds. This is a cash reconciliation, not a profit calculation. Remaining stock, credit purchases, loan movements and household drawings must still be considered before interpreting the day’s result.
Tomorrow’s buying decision follows from that review. In this example, the seller checks which vegetables remain before preparing another purchase list. The goal is not to borrow the maximum amount available, but to connect the next stock order with actual selling needs and repayment capacity.
Interest, Subsidy and the Cost of Borrowing
The scheme provides a 7% annual interest subsidy to incentivise regular repayment. This subsidy is not the same as saying that the lender charges 7% interest, and it does not make the government loan interest-free. Confirm the applicable lending rate, repayment schedule and subsidy conditions before accepting an offer.
Ask for the terms in writing. In particular, check the instalment amount, total repayment obligation, first due date and any applicable documentation or other charges. Bank of Maharashtra’s published product information lists nil processing and prepayment charges, while noting that documentation or other charges follow its applicable guidelines. These details should not be assumed to be identical across all lenders.
For this illustrative seller, the budgeting approach is to plan around the scheduled instalment rather than an anticipated incentive credit. Keep subsidy receipts separate in the ledger so they are not mistaken for customer sales. Likewise, do not count a possible cashback benefit as money already available for the next day’s stock.
Prepare the Application Before the Next Market Day
Under the revised operational guidelines, eligible applicants include vendors with a valid Certificate of Vending, vendor ID or Letter of Recommendation issued through the relevant local authority arrangements. Coverage progressively includes census towns and peri-urban areas, with an approved Letter of Recommendation route through the Block Development Officer where applicable.
Prepare the following documents before starting the PM SVANidhi loan application:
- Vendor documentation: The applicable Certificate of Vending, ID card or approved Letter of Recommendation.
- Identity document: Aadhaar, with the specified Voter ID alternative for qualifying applicants in Assam and Meghalaya who do not have Aadhaar.
- Bank details: Savings account passbook or statement showing the applicant’s account information.
- UPI details: A valid, unique UPI ID linked to the vendor’s bank account.
The current guidelines specify these documents and require Letters of Recommendation to be applied for and issued through the scheme portal. Manually issued letters are not valid.
For readers searching for ‘PM SVANidhi loan apply online’, the application route is the official PM SVANidhi portal. Vendors who need a Letter of Recommendation can use the LoR-cum-loan application process, with assistance available through local-body or block offices and authorised Common Service Centres. Submitting an application does not guarantee loan approval.
If your search is ‘PM SVANidhi loan Rs 50,000 apply online’, remember that Rs 50,000 is the third-tranche ceiling, not the standard first loan. Full repayment of the previous tranche is required before accessing the next one. Check that a completed loan has been correctly marked as closed before pursuing the next application.
For those searching ‘PM SVANidhi loan Rs 50,000 apply online last date’, the relevant national lending-period extension runs until March 31, 2030. This does not guarantee approval or disbursement by a particular date. Confirm your application status and the latest instructions through official channels.
Read Scheme Material, Municipal Records and Ledgers Together
Each source answers a different question. Scheme material describes the lending framework, municipal records explain local administration and progress, and a vendor’s ledger shows that individual business’s transactions. None should substitute for the others.
The public PMC citizen dashboard provides municipal reporting categories for eligible applications, sanctions, bank disbursements and pending disbursements. Its separation of these stages is useful: an application, a sanction and money reaching an account are different events. This article does not use its aggregate figures to make claims about the illustrative seller.
The vendor-ledger table above is an illustrative recording framework, not a source document obtained from an actual vendor. A reported version would require consent specifically covering the review of the ledger, matching bank transactions and publication of agreed details. Exclude names, account numbers and identifiable transaction details unless the relevant authority expressly permits their publication.
The exact supplied address could not be retrieved and is not used as evidence. Verified PIB announcements, operational guidelines, lender material and the municipal dashboard support the factual information presented here. No private ledger has been independently reviewed.
Take the Next Step With a Clear Borrowing Plan
For vendors exploring microcredit in India, start with the stock cycle rather than the largest advertised amount. Write down what needs financing, what remains unsold and what the business can set aside for repayments. Use your own records, not this illustration, to assess those decisions.
PM SVANidhi connects street vendors in India’s informal economy with a formal working capital loan route. The useful next step is to prepare the required documents, approach the official portal or an authorised assistance point, and review the lender’s terms before accepting credit.
Prepare your documents, reconcile your accounts and begin through the official PM SVANidhi application channel.
Also Read: Digital Payments: Lessons From A Tea Stall’s QR Code
To read more such news, download Bharat Express news apps