

AI Generated Image
India and Malaysia are turning semiconductor cooperation into a practical bridge between national industrial strategy, ASEAN supply-chain depth, and the wider BRICS economic orbit. India brings market scale, design talent, new public incentives, and an ambition to localise more of the chip value chain; Malaysia brings decades of electronics manufacturing experience, a strong E&E base, and a growing push into IC design and advanced semiconductor capabilities. Together, they show how ‘silicon bridges in BRICS’ can mean more than diplomacy: they can mean talent pipelines, packaging capacity, trusted trade routes, and co-investment.
Why Does the India–Malaysia Semiconductor Partnership Matter Now?
The partnership matters because semiconductors have become a test of economic resilience, not just a technology input. Chips sit inside phones, vehicles, industrial systems, healthcare equipment, defence platforms, cloud infrastructure, and AI hardware, so disruptions now affect national competitiveness and public services. India and Malaysia are aligning at a moment when governments and companies are trying to diversify supply chains away from excessive concentration and create more trusted, regionally connected production networks.
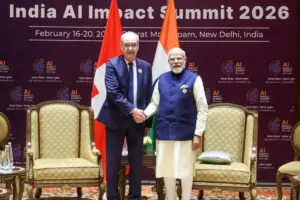
The political signal has become clearer. On September 12, 2026, Malaysian Prime Minister Anwar Ibrahim and Indian Prime Minister Narendra Modi discussed deeper semiconductor cooperation, integrated supply chains, talent development, two-way investment, and industry partnerships on the sidelines of the 18th BRICS Leaders’ Summit in New Delhi. Malaysia attended the summit as a BRICS Partner Country, a status it has held since January 1, 2025.
The BRICS Orbit Adds a Wider Strategic Frame
BRICS does not replace bilateral agreements, ASEAN platforms, or Western technology partnerships. Its value here is different: it gives emerging economies another venue to discuss industrial resilience, financing, trade facilitation, standards, and South–South cooperation. India is a full BRICS member, while Malaysia’s partner-country status gives Kuala Lumpur a channel into BRICS discussions without requiring it to abandon its non-aligned, ASEAN-centred foreign policy.
For semiconductors, that matters because no country can build the entire value chain alone. The sector depends on design tools, specialised materials, fabs, outsourced assembly and testing, advanced packaging, skilled engineers, equipment vendors, logistics, clean energy, and stable regulation. The ‘BRICS orbit’ becomes useful when it encourages complementary roles rather than unrealistic self-sufficiency.
India’s Role in the Silicon Bridge
India’s semiconductor strategy is built around moving from consumption and design strength towards a deeper manufacturing and packaging ecosystem. The Government of India approved a Rs 76,000 crore programme for semiconductor and display manufacturing and created the India Semiconductor Mission to drive long-term ecosystem development. The programme covers fabs, display fabs, compound semiconductors, silicon photonics, sensors, ATMP/OSAT facilities, and semiconductor design incentives.
Recent official material from India also points to a broader pipeline: SEMICON India 2025 highlighted 10 approved strategic semiconductor projects across high-volume fabs, advanced packaging, compound semiconductors, OSATs, research, and startups. India’s focus is not only on fabrication; it is also trying to build design capability, packaging capacity, supply-chain inputs, and workforce depth.
This makes Malaysia a logical partner. India needs experienced manufacturing ecosystems, practical exposure to global E&E operations, and pathways for companies to plug into regional supply chains. Malaysia can help connect Indian firms and engineers to a mature electronics cluster while benefiting from India’s expanding market, engineering base, and policy momentum.
Malaysia’s Role as an Electronics and Design Hub
Malaysia has long been a major electronics and electrical manufacturing location, especially in assembly, testing, and related supply-chain services. Its current challenge is to move into higher-value activities, including IC design, advanced packaging, and locally developed semiconductor products. That ambition is visible in Malaysia’s four-year strategic partnership with Arm, which includes plans to train 10,000 IC design engineers and provide selected Malaysian companies with access to Arm technology and IP.
Malaysia’s advantage is operational realism. It understands factory ecosystems, supplier development, export logistics, workforce training, and multinational investment relationships. For India, this experience can shorten learning curves. For Malaysia, India offers a huge downstream market and a partner that is actively building new semiconductor capacity.
Where the Partnership Can Become Practical
The most credible India–Malaysia semiconductor agenda is not a single mega-project. It is a portfolio of connected actions that reduce supply-chain fragility and create business reasons for companies to cooperate.
Key areas include:
- Talent mobility and joint training: Indian engineering institutions and Malaysian industry programmes can support practical skills in IC design, packaging, testing, reliability, embedded systems, and manufacturing operations.
- OSAT and advanced packaging collaboration: Malaysia’s established back-end ecosystem can complement India’s new packaging and testing investments.
- Design-to-manufacturing pathways: Indian design teams can work with Malaysian partners on prototyping, validation, test flows, and productisation.
- Supplier development: Smaller firms in chemicals, precision components, automation, logistics, and maintenance can be linked into cross-border semiconductor supply chains.
- Two-way investment: Malaysian companies can explore India’s expanding electronics market, while Indian firms can use Malaysia as a Southeast Asian production and partnership base.
- Standards and trust: Both countries can cooperate on quality systems, traceability, cybersecurity for electronics, and resilient sourcing.
How Can ‘Silicon Bridges in BRICS’ Avoid Becoming Just a Slogan?
The phrase becomes meaningful only if policy conversations lead to bankable projects, skilled workers, and reliable production links. That means India and Malaysia should prioritise implementation over announcements: identify specific segments, match companies with institutions, and measure progress through training output, supplier contracts, pilot lines, and investment flows.
A practical roadmap would include five steps:
- Map complementary capabilities across design, ATMP, OSAT, equipment services, materials, and logistics.
- Create industry working groups that include startups, manufacturers, universities, and investment agencies, not only Ministries.
- Build shared training programmes with curricula tied to actual fabless, packaging, and testing roles.
- Support pilot projects that prove cross-border workflows before scaling.
- Use BRICS and ASEAN forums to improve financing, market access, and coordination while keeping technical cooperation business-led.
This approach also keeps expectations grounded. Neither India nor Malaysia needs to claim dominance across the whole semiconductor chain. The stronger goal is resilience through specialisation: each partner becomes more valuable because it strengthens a specific part of a larger network.
Risks That Need Careful Management
The partnership faces real constraints. Semiconductor projects require large capital commitments, long timelines, specialised utilities, advanced equipment, and patient execution. Talent shortages can slow growth, and export controls or technology licensing limits may shape what firms can share across borders.
There is also a coordination risk. India’s semiconductor mission, Malaysia’s national semiconductor ambitions, ASEAN trade processes, BRICS diplomacy, and private-sector investment cycles all move at different speeds. If the two countries do not create clear project-level mechanisms, cooperation can remain trapped in summit language.
A useful checklist for policymakers and companies would include:
- Are priority segments defined clearly enough for investors?
- Are training programmes tied to jobs that companies are ready to offer?
- Are customs, standards, and certification processes predictable?
- Are universities connected to industry roadmaps rather than generic skilling goals?
- Are small and mid-sized suppliers included, or only large anchor firms?
- Are IP, data security, and export-control issues addressed early?
The Larger Opportunity
India–Malaysia semiconductor cooperation is best understood as a bridge between ambition and capability. India is building scale, incentives, and strategic demand; Malaysia is adding manufacturing depth, E&E credibility, and a sharper design agenda. The BRICS orbit gives the relationship a wider geopolitical frame, but the real work will happen in factories, labs, classrooms, supplier networks, and investment decisions.
If both countries stay focused on execution, ‘silicon bridges in BRICS’ can become a model for how emerging economies secure semiconductor chains without trying to duplicate every part of the industry. The strongest bridge will not be symbolic. It will be modular, commercially useful, and built one talent programme, supplier link, packaging project, and trusted partnership at a time.
To read more such news, download Bharat Express news apps